Escrow Platform for Businesses: Fix Fund Diversion, Delays & Compliance Risk
Escrow is supposed to make transactions safer — a neutral place to hold funds until both sides deliver on their end of the deal. But when that process runs on spreadsheets, email approvals, and manual bank transfers, it often creates the exact problems it was meant to prevent: diverted funds, delayed settlements, and compliance gaps that put your business at risk.
A modern escrow platform replaces that manual process with segregated, secure accounts, automated conditional releases, and built-in compliance — so businesses can hold and move funds with confidence, not guesswork.
Table of Contents
What is an Escrow Platform?
Why Do Businesses Struggle with Manual Escrow
How Does an Escrow Platform Solve Fund Diversion Risk?
How Does an Escrow Platform Speed Up Payment Settlements?
Can an Escrow Platform Handle Multi-Party Payments?
How Does an Escrow Platform Support Compliance?
Does an Escrow Platform Provide Transparency Into Fund Movement?
What Should Businesses Look for in the Best Escrow Platform?
Frequently Asked Questions
What Is an Escrow Platform?
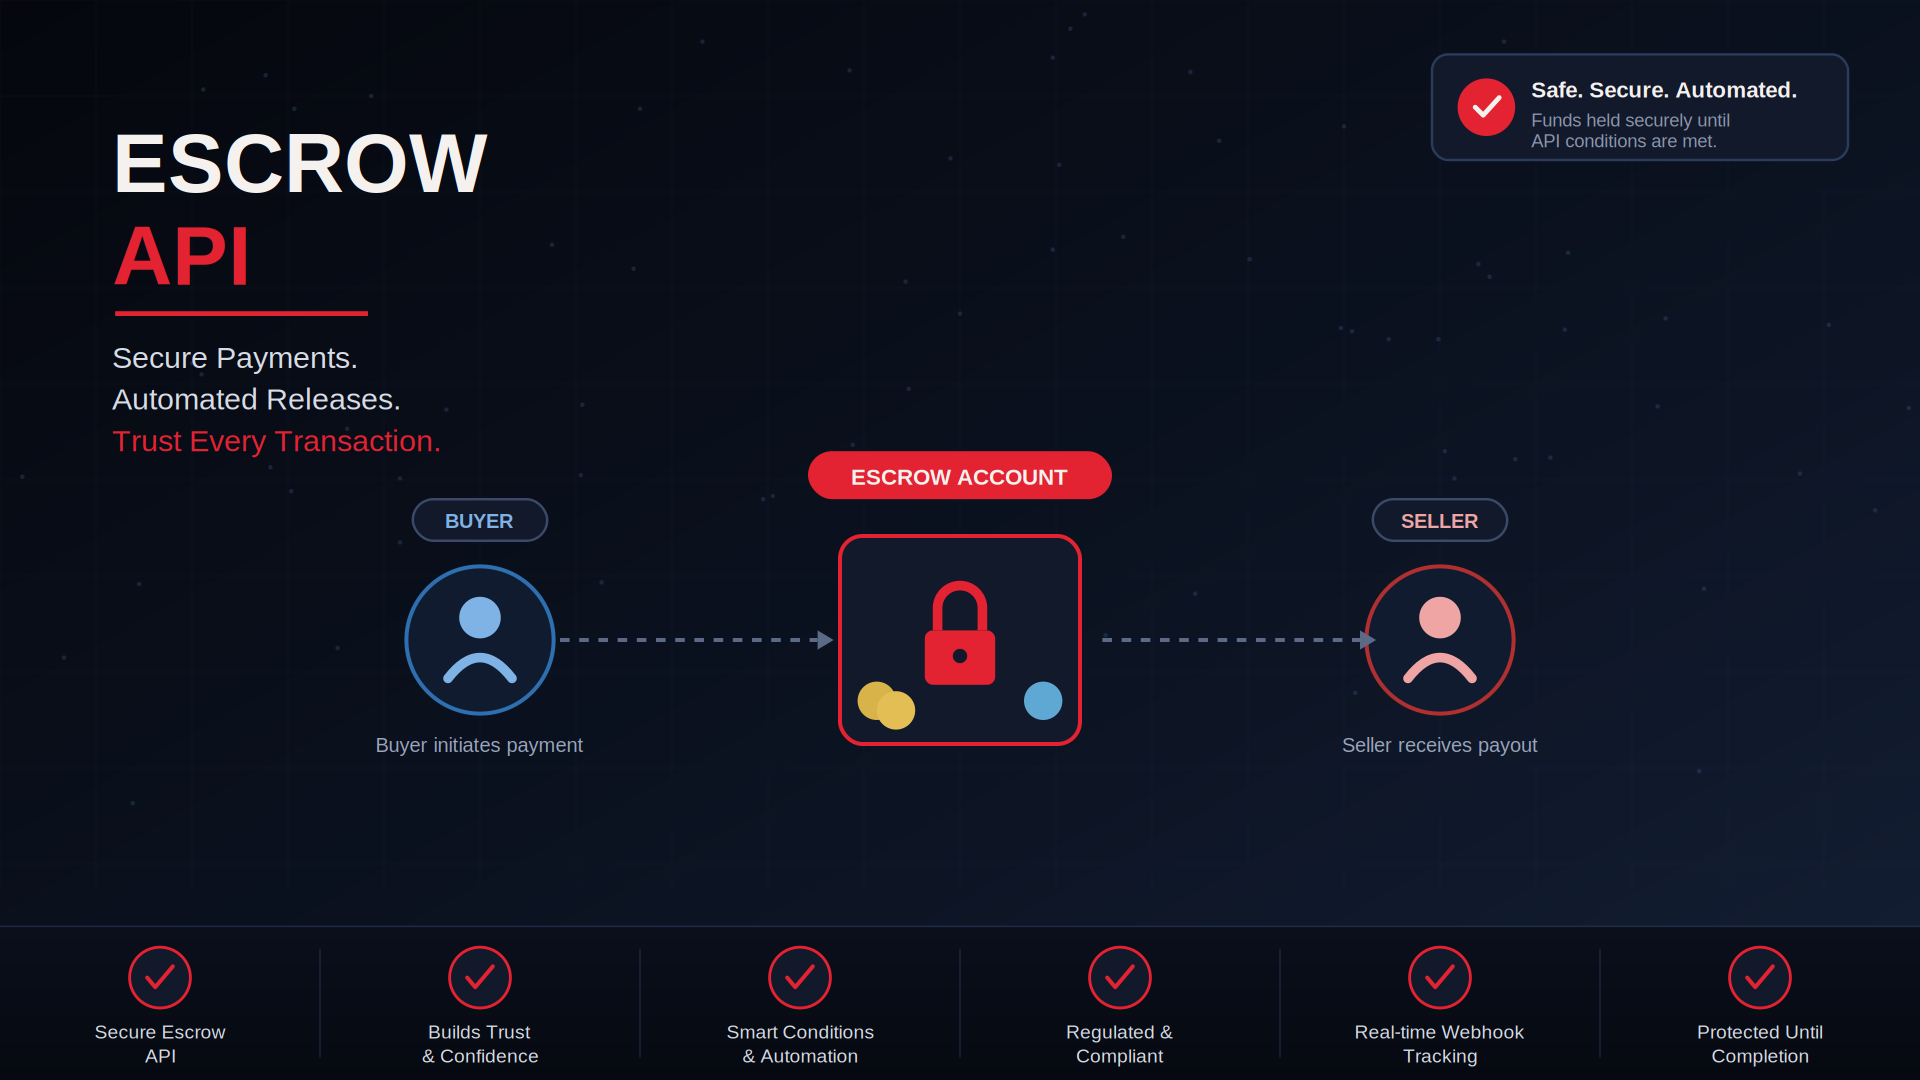
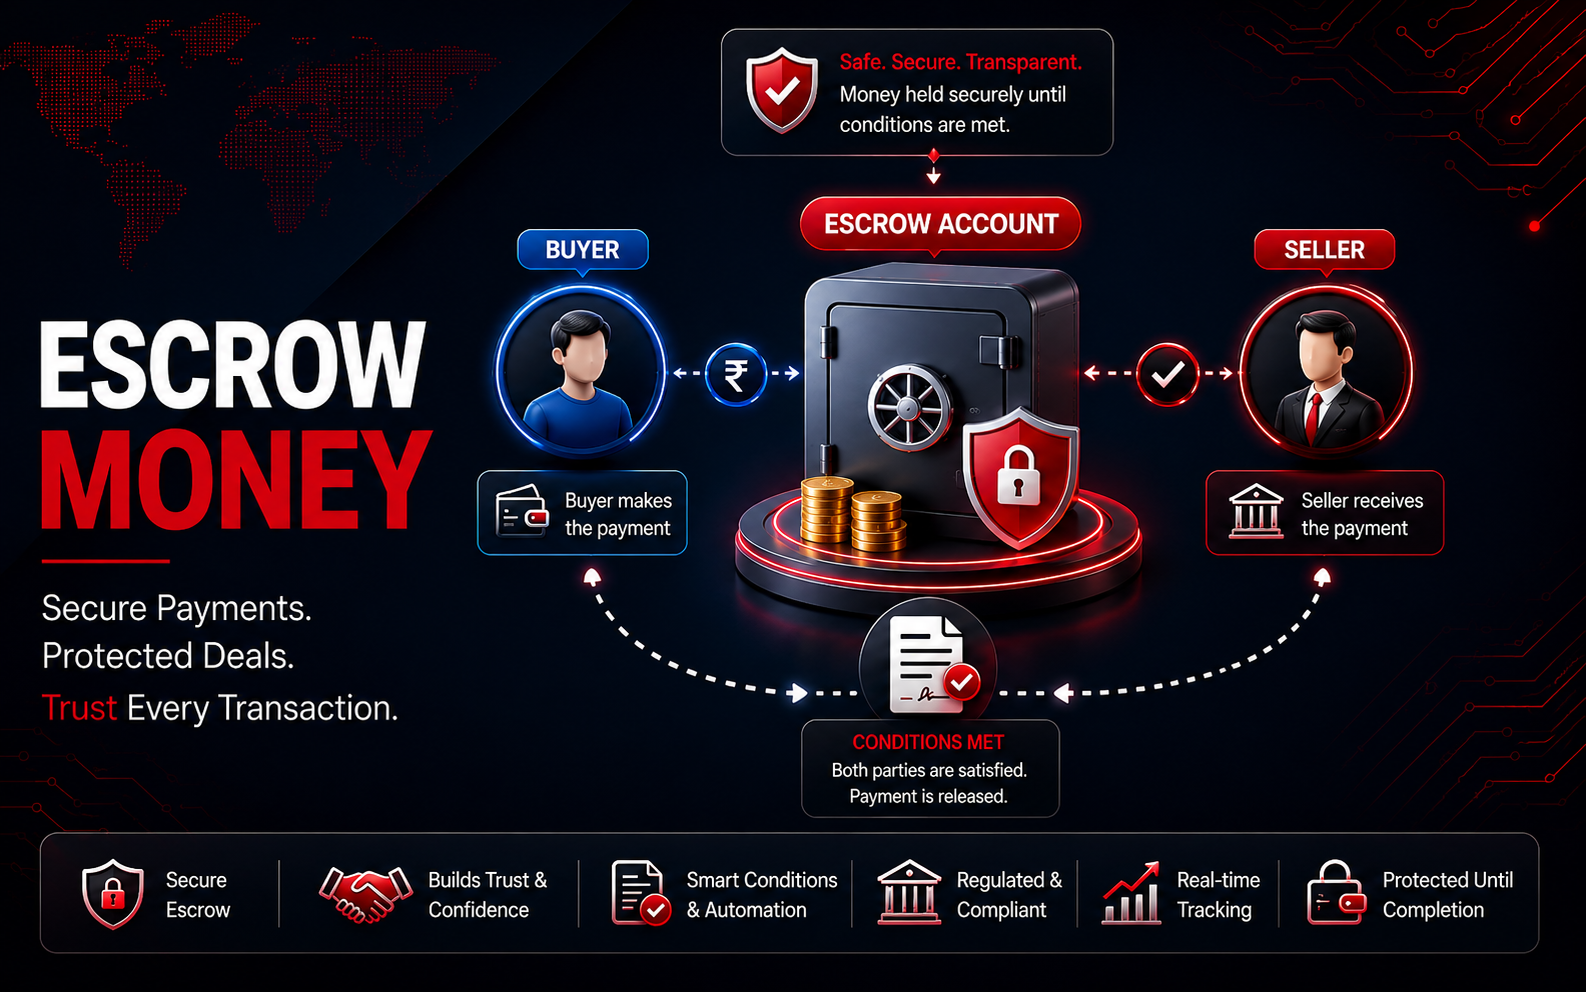
An Escrow platform is a secure, third-party system that holds funds on behalf of two transacting parties and releases them only once pre-agreed conditions are met. Unlike manual escrow — which relies on spreadsheets, email approvals, and bank transfers — an escrow platform automates fund holding, verification, and release, removing the risk and delay that come with handling escrow by hand.
Businesses use escrow platforms for transactions where trust, timing, or compliance is critical: M&A deals, marketplace payouts, freelance and vendor contracts, and multi-party agreements.
Why Do Businesses Struggle With Manual Escrow?
Manual escrow fails businesses because it depends on people, not systems — creating delays, errors, and risk at every step. The most common failure points are:
Lack of trust between parties — no verifiable proof funds are actually secured
Manual account management — spreadsheets and email threads instead of a system of record
Delayed settlements — funds sit longer than necessary due to manual approvals
Fund diversion risk — no segregated accounts or access controls
Complex multi-party distribution — near-impossible to split funds accurately by hand
Manual reconciliation — time-consuming, error-prone matching of records
Compliance gaps — KYC/AML and reporting requirements are hard to track manually
No transparency — neither party can see real-time fund status
No conditional automation — milestone-based releases aren't enforced consistently
How Does an Escrow Platform Solve Fund Diversion Risk?
An escrow platform prevents fund diversion by holding money in segregated accounts with strict, auditable access controls, so funds cannot move until contractual conditions are independently verified. This removes the possibility of commingling or premature access that manual escrow accounts are exposed to.
How Does an Escrow Platform Speed Up Payment Settlements?
An escrow platform speeds up settlements by automating fund release the moment agreed conditions are met, instead of waiting on manual approval chains. Release triggers can be tied to milestones, deliverables, or multi-party sign-off — cutting the delay that comes from manual processing.
Can an Escrow Platform Handle Multi-Party Payments?
Yes — a modern escrow platform automatically distributes funds across multiple stakeholders based on pre-set rules, without manual splitting. This is critical for marketplaces, syndicated deals, and vendor networks, where a single transaction must pay out to several parties accurately and on schedule.
How Does an Escrow Platform Support Compliance?
An escrow platform supports compliance by handling KYC checks, AML monitoring, and jurisdiction-specific reporting automatically, in the background. This reduces the exposure businesses face when trying to track evolving regulatory requirements manually — especially across multiple regions.
Does an Escrow Platform Provide Transparency Into Fund Movement?
Yes — escrow platforms give both parties real-time visibility into fund status through a shared dashboard, removing the need for manual status checks, emails, or support tickets to answer "where's my money?"
What Should Businesses Look for in the Best Escrow Platform?
The best escrow platform for businesses combines segregated fund security, automated conditional releases, multi-party distribution, built-in compliance, and real-time transparency in one system. When evaluating options, businesses should prioritize:
Segregated, audited accounts (not commingled funds)
Automated milestone- or condition-based releases
Support for multi-party payment splits
Built-in KYC/AML and regulatory reporting
Real-time dashboards for both parties
Automated reconciliation instead of manual matching
API access for integration into existing workflows
Frequently Asked Questions
What is the difference between an escrow platform and a payment processor?
A payment processor simply moves money between parties. An escrow platform holds funds in a secure, segregated account and releases them only once specific, agreed-upon conditions are verified — adding a layer of protection that payment processors don't provide.
Is an escrow platform the same as escrow software?
Escrow software refers to the technology used to manage escrow transactions, while an escrow platform is the full service — software plus the secured accounts, compliance handling, and infrastructure needed to hold and release funds. In practice, the terms are often used interchangeably.
How quickly are funds released on an escrow platform?
Funds are typically released automatically once the pre-defined condition — such as delivery confirmation or milestone approval — is met, rather than waiting on manual sign-off.
Do escrow platforms handle regulatory compliance?
Yes, most dedicated escrow platforms manage KYC, AML, and jurisdiction-specific reporting requirements as part of the service, reducing the compliance burden on the businesses using them.
Can an escrow platform split payments between multiple parties?
Yes, platforms built for multi-party distribution can automatically route funds to several stakeholders based on pre-set rules, which is common in marketplace and syndicated-deal use cases.